By Fatima Saka
The Senate on Thursday advanced efforts to tighten oversight of Nigeria’s rapidly expanding fintech sector, as it considered for second reading a bill seeking to amend the Banks and Other Financial Institutions Act (BOFIA) to provide for the designation, registration and enhanced supervision of systemically important financial institutions.
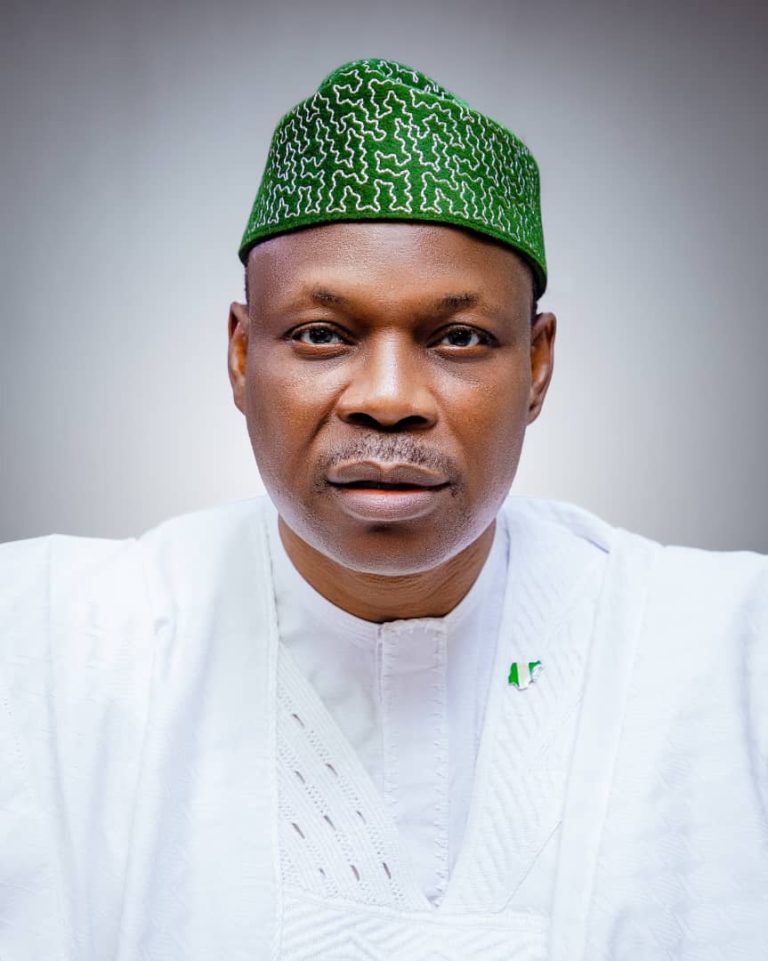
Leading the debate on the bill titled “A Bill for an Act to Amend the Banks and Other Financial Institutions Act… (SB. 959)”, Senator Mukhail Adetokunbo Abiru (Lagos East) warned that Nigeria’s legal and regulatory framework has failed to keep pace with the fast-growing influence of fintech companies and other technology-driven financial service providers.
According to Abiru, while BOFIA 2020 currently empowers the Central Bank of Nigeria (CBN) to designate systemically important institutions, the scope is focused mainly on deposit money banks, creating a dangerous regulatory gap.
“Today, non-bank institutions, by virtue of their scale, data concentration, customer reach and technological capacity, can pose risks equal to or even greater than those of traditional banks,” he said. “Yet, they operate outside the highest tier of statutory oversight.”
The senator stressed that some fintechs now process transactions rivaling those of mid-sized banks, serving tens of millions of Nigerians while holding vast pools of sensitive personal and financial data. Of equal concern, he said, is the involvement of foreign networks, offshore data storage, and opaque ownership structures, which complicate regulatory visibility and threaten Nigeria’s data sovereignty.
“In the digital economy, data is no longer just an administrative asset. It is a strategic national resource. Sadly, we cannot even say with certainty where all financial and behavioural data are stored or which jurisdiction may lay claim to them,” Abiru added.
He explained that the proposed amendment would empower the CBN to designate fintechs, digital lenders, payment intermediaries and other tech-based institutions as systemically important where their operations pose risks to national security and financial stability. It would also establish a national registry to ensure transparency, continuous disclosure of beneficial ownership and stricter, risk-based supervision.
Other lawmakers threw their weight behind the bill, emphasising its importance to national security and consumer protection.
Senator Victor Umeh (Anambra Central) argued that many criminal networks now exploit fintech platforms to receive ransoms and carry out illicit transactions without a traceable trail.
“These kidnappers no longer use conventional banks. They use fintech platforms where there is little or no oversight. This bill will ensure that nobody operates without a traceable identity and proper regulatory compliance,” he said.
Senators also raised concerns over online loan sharks and fraudulent digital lending platforms that access victims’ bank accounts without authorisation, plunging Nigerians into debt and despair.
“The government is losing tax on interest, innocent citizens are losing their savings, and these institutions don’t even have a physical presence or pay tax in Nigeria,” one senator noted, calling for stronger insurance and consumer protection measures under the new law.
Senator Natasha Akpoti-Uduaghan (Kogi Central) added an economic dimension to the debate, decrying the huge disparity between what Nigerian and foreign content creators earn on global platforms such as Facebook.
She attributed this gap largely to weak payment systems and regulatory frameworks, expressing hope that the bill would help create fairer, more structured online transaction systems for Nigerian youths.
Lawmakers agreed that relying solely on CBN regulations, which lack the force of law, was no longer sufficient.
“Regulations do not have the same weight as an Act of Parliament. If these companies collapse tomorrow, the government will bear the burden of rescuing millions of affected Nigerians,” a senator warned.
At the end of deliberations, the Senate expressed broad support for the bill, describing it as timely, necessary and critical to protecting Nigeria’s financial system, data sovereignty and national security in an increasingly digital economy. The bill was subsequently passed second reading and referred to the committee on Banking, Insurance and Other Financial Institutions for further legislative action.
About The Author